Running a small business involves juggling customers, invoices, suppliers, employees and countless other responsibilities. With so much to manage, bookkeeping can sometimes fall to the bottom of your to-do list. However, ignoring important bookkeeping tasks can lead to inaccurate financial records, cash flow problems and unnecessary stress when tax time arrives.
Good bookkeeping is about more than keeping receipts in a folder. It helps you understand where your money goes, monitor business performance and maintain organised financial records throughout the year.
For Australian small business owners, regular bookkeeping can also support GST reporting, Business Activity Statement (BAS) preparation and other financial obligations.
So, which bookkeeping tasks should you never ignore? Let’s explore the essential tasks that help keep your business finances organised and running smoothly.
1. Bank Reconciliation
Bank reconciliation is one of the most important bookkeeping tasks for any small business.
It involves comparing the transactions recorded in your accounting software with those shown on your bank statements. The aim is to ensure your records accurately reflect the money moving in and out of your business.
Without regular bank reconciliation, missing transactions, duplicate entries and incorrect amounts can go unnoticed for months.
For example, you might accidentally record a supplier payment twice or forget to enter a bank fee. These small errors can affect your financial reports and make it harder to understand your true financial position.
Reconciling your bank accounts regularly helps identify discrepancies early and gives you greater confidence in your financial information.
Tip: Schedule a regular time each week or month to review your transactions, depending on your business’s size and activity.
2. Recording Business Income and Expenses
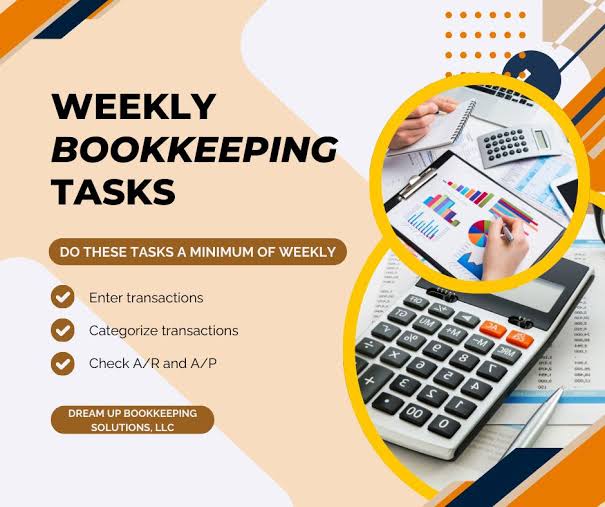
Every business transaction needs to be recorded accurately and categorised correctly.
This includes sales income, supplier payments, rent, insurance, software subscriptions, travel costs and other business expenses.
When transactions are recorded inconsistently or left until the end of the financial year, it becomes much harder to understand your spending and calculate your business performance.
Accurate expense tracking also helps you identify unnecessary costs and maintain supporting records for tax purposes.
For example, reviewing your monthly expenses may reveal that you are paying for software subscriptions you no longer use.
Keeping income and expenses up to date allows you to see where your money is going and make informed decisions about your business spending.
3. Keeping Receipts and Supporting Documents
Receipts, invoices and other supporting documents are essential parts of good bookkeeping.
They provide evidence of business transactions and help explain how amounts have been recorded in your accounts.
If you lose a receipt or cannot identify a transaction, it may become difficult to confirm whether an expense is business-related or whether the correct GST treatment has been applied.
Australian businesses should keep records that support their income, expenses and tax reporting obligations. The Australian Taxation Office generally requires many business tax records to be kept for at least five years, although specific retention periods can vary depending on the record and circumstances.
Digital recordkeeping can make this process easier. You can use accounting software or secure document storage to organise invoices and receipts as they arrive.
Tip: Avoid leaving receipts in your car, wallet or email inbox. Save them in a consistent place as soon as possible.
4. Tracking Accounts Receivable
Accounts receivable refers to money customers owe your business for products or services you have provided.
Ignoring unpaid invoices can create cash flow problems, even when your business is generating healthy sales.
For example, you might issue several invoices during the month but receive payment from only a small number of customers. Meanwhile, rent, supplier bills and other expenses still need to be paid.
Regularly reviewing accounts receivable helps you identify overdue invoices and follow up with customers before payments become significantly delayed.
It also helps you understand how much money is expected to come into your business and when you may receive it.
Consider setting clear payment terms, sending invoices promptly and establishing a consistent process for following up overdue accounts.
5. Monitoring Accounts Payable
While collecting money is important, keeping track of what your business owes is equally essential.
Accounts payable refers to outstanding amounts owed to suppliers and other creditors.
If you fail to monitor these payments, you could miss due dates, incur late fees or damage relationships with suppliers.
Maintaining an up-to-date list of unpaid bills helps you plan upcoming payments and avoid unnecessary financial pressure.
It also gives you a clearer understanding of your short-term financial commitments.
Review your supplier invoices regularly, check due dates and ensure payments are recorded correctly once made.
A well-maintained accounts payable process helps you manage obligations without losing track of the money available in your business bank account.
6. Reviewing GST and BAS Records
For businesses registered for GST, maintaining accurate GST records is an essential bookkeeping responsibility.
Your records should clearly show relevant sales, purchases, GST collected and eligible GST credits, based on the applicable rules.
Errors in transaction categorisation or missing tax invoices can affect the accuracy of your Business Activity Statement (BAS).
Leaving GST checks until the reporting deadline can also create unnecessary stress and increase the likelihood of mistakes.
Regularly reviewing your transactions helps identify missing information and potential errors before BAS preparation.
Depending on your business arrangements, a bookkeeper may maintain your records and prepare supporting reports. BAS services must be provided by an appropriately registered BAS agent where registration is required.
Tip: Keep your bookkeeping current throughout the reporting period rather than trying to organise several months of transactions at once.
7. Managing Payroll Records
If your business employs staff, payroll recordkeeping is another task you should never overlook.
Depending on your arrangements, payroll bookkeeping may involve recording wages, reconciling payroll transactions, tracking PAYG withholding and maintaining records relating to superannuation and employee entitlements.
Australian employers also need to understand their applicable Single Touch Payroll (STP) reporting obligations.
Payroll mistakes can affect employees’ pay and create additional administrative work for your business.
Regularly checking payroll reports against your accounting records can help identify discrepancies early.
Because employment and payroll obligations can be complex, seek appropriate professional advice when you are unsure about your responsibilities.
8. Monitoring Cash Flow
Cash flow is the movement of money into and out of your business. Ignoring it can make even a profitable business vulnerable to financial difficulties.
Your profit and loss statement may show a profit, but that does not necessarily mean you have enough cash available to pay your bills.
Customers may pay late, stock purchases may tie up funds, or several major expenses may fall due at the same time.
Reviewing cash flow regularly helps you anticipate upcoming expenses and understand whether expected income will cover your commitments.
Maintain a record of incoming payments, upcoming bills and anticipated tax obligations. Where possible, plan ahead for periods when sales may be slower.
Understanding your cash flow helps you make better decisions about spending, hiring and business growth.
9. Reviewing Financial Reports
Financial reports help you understand how your business is performing.
Two important reports are the profit and loss statement and the balance sheet.
Your profit and loss statement summarises income and expenses over a period, helping you understand whether your business has generated a profit or loss.
Your balance sheet provides a snapshot of your assets, liabilities and equity at a particular date.
Reviewing these reports regularly can help you identify rising expenses, changes in profitability and potential financial issues.
Rather than looking at your reports only at tax time, make them part of your monthly business review.
Use the information to ask practical questions: Are expenses increasing? Are customers paying on time? Is profit improving? Do you have enough cash to meet upcoming commitments?
10. Keeping Your Bookkeeping Up to Date
Perhaps the most important bookkeeping task of all is consistency.
When bookkeeping is neglected for weeks or months, transactions accumulate, receipts go missing and unanswered questions become harder to resolve.
Catching up can take considerable time and may delay the preparation of financial reports or BAS information.
Maintaining your books regularly makes it easier to identify problems, keep records organised and understand your business finances.
Create a bookkeeping schedule that fits your business, whether that means updating transactions weekly, reconciling accounts monthly or reviewing reports at the end of each month.
If you find it difficult to keep up, professional bookkeeping support can help you maintain accurate records and free up time to focus on running your business.
Conclusion: Make Bookkeeping a Business Priority
The bookkeeping tasks you should never ignore are the ones that keep your financial records accurate, organised and useful.
From bank reconciliation and expense tracking to unpaid invoices, GST records, payroll and cash flow monitoring, every task plays a role in maintaining a clear picture of your business finances.
Small bookkeeping issues can become bigger problems when left unresolved. By developing consistent habits and reviewing your records regularly, you can reduce errors, improve financial visibility and prepare for reporting deadlines with greater confidence.
Need help keeping your books up to date? Professional bookkeeping support can help you manage everyday transactions, maintain organised financial records and understand your business’s financial position.
Don’t wait until tax time to catch up. Make bookkeeping a regular part of your business routine and give yourself more time to focus on growth.